

In short
- Swift is fast between large banks, but payments in the retail category, which includes B2B, are much slower to reach the final account.
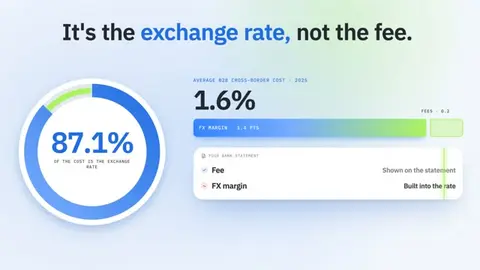
- Most of the cost of a cross-border B2B payment is the exchange-rate margin, not the sending fee.
- A licensed stablecoin route beats Swift in roughly half of the corridors from the EU, mainly where Swift is slow: Nigeria, Mexico, US payments at weekends.
- It does not make sense inside SEPA, and local rules make it impractical in Turkey, India, China and Brazil.
A EUR 20,000 invoice paid to a supplier outside Europe still takes a day or more to arrive, and most of what it costs is hidden in the exchange rate, not in the fee on your bank statement. That is the picture from the Financial Stability Board's own monitoring of cross-border payments for business, the data the G20 uses to track its 2027 targets.
The reasons are structural. Money moves through a chain of banks, each running its own checks in turn, on business days only. Inside the euro area the problem is largely solved: SEPA Instant credits a transfer in seconds. Outside it, or in another currency, the old chain still applies.
This guide explains where the time and money go in cross-border B2B payments, how a stablecoin route compares with Swift corridor by corridor from the EU, and what the EU's instant payments rules change. It also covers where stablecoins do not help and add risk instead.
How does a cross-border B2B payment work?#
A domestic transfer settles in one place: both banks hold accounts at the same central bank, and the central bank moves reserves between them. A cross-border payment has no such common ground. When two currencies are involved, there is no single settlement asset both banks can use, so the payment becomes a series of account updates across several institutions.
The BIS describes the typical case in its May 2024 bulletin on correspondent banking. A US firm pays a Korean supplier. The US bank pays a correspondent bank in dollars inside the US system. The correspondent credits the Korean bank's dollar account (its "nostro" account). The Korean bank then sees the funds and credits the supplier in won. Settlement only ever happens in the US; everything else is messages and book entries.
Each link in that chain screens the payment for sanctions, AML and data quality before passing it on. The BIS authors put it plainly:
"The burden of performing these checks is placed on individual banks, who follow a sequential process that takes time and involves significant duplication of effort."
Then there is the calendar. Each bank works to its own cut-off times and business days, so a payment sent on Friday afternoon may not move until Monday, and a public holiday in either country adds a day.
The last bank is often the slowest. The FSB's 2025 report notes that the beneficiary leg, the time between the receiving bank getting the instruction and crediting its customer, "has traditionally been the slowest part of a cross-border payment transaction."
And the chain is getting thinner. According to the BIS, correspondent banking relationships fell by about 25% between 2011 and 2020, and the decline continued into 2022. Fewer direct links mean longer routes, especially into smaller markets.
Why are cross-border B2B payments so expensive?#
For a company, the cost of a cross-border payment is mostly the exchange rate. According to the FSB's 2025 consolidated progress report, the average cost of a B2B cross-border payment was 1.6% in 2025, measured on a USD 20,000 payment with data from FXC Intelligence as of March 2025. Of that, 1.4 percentage points came from the FX margin and only 0.2 from fees. The exchange rate made up 87.1% of the total.
That explains why a "low-fee" wire can still be expensive. The fee is visible on the statement; the margin is built into the rate and rarely shown separately. The same report adds that when the receiving bank also converts the money, receiver-side FX margins add another 0.7% to 1.1% on average.
Price transparency is still weak. Only 43.2% of B2B payment services in the FSB sample showed both cost and speed to the customer in 2025, against 73.7% for person-to-person services.
How long do cross-border B2B payments take to arrive?#
Large payments between banks are fast. Payments in the retail category, which includes B2B, are not. Swift data in the FSB report show that 54.6% of wholesale cross-border payments (USD 100,000 and above) were credited within one hour in 2025, and 93.2% within one business day.
The retail figures tell a different story. Among B2B services that disclose speed, only 2.2% credited the recipient within one hour in 2025, and 39.6% within one business day. Europe does better on price than other regions, with retail costs of 1% to 1.9% depending on the use case. Speed is still low: about 5% of B2B and B2P payments sent from Europe and Central Asia arrived within one hour.
The G20 target for retail payments, which include B2B, is a global average cost of no more than 1% and 75% of payments available to the recipient within one hour by end-2027. The FSB does not expect to get there:
"It is unlikely that satisfactory improvements at the global level will be achieved in line with the 2027 Roadmap timetable."
For a treasury team this has a practical meaning. Plan around today's payment infrastructure for at least the next few years.
Is a stablecoin route better than Swift?#
A stablecoin route, sometimes called a stablecoin sandwich, replaces the correspondent chain with three steps. A licensed provider converts your euros into a dollar stablecoin such as USDC (a crypto-asset that tracks the US dollar), the stablecoin moves on a public blockchain, and a provider in the supplier's country converts it into local currency and pays out. Against Swift from the EU, it works or can work in about half of the corridors we looked at. Where it wins, the reason is usually speed and access, not price. The on-chain transfer takes minutes at any hour, while a wire waits for cut-offs and for the last bank to credit its customer. The price gain is modest in major currencies and can vanish in exotic ones, because converting into local currency at the far end costs the most. Local rules decide the rest: some countries leave the route open, some require a licensed local partner, and a few close it.
Key moments
| Swift wire | Stablecoin route | |
|---|---|---|
| Path | Your bank, one or more correspondent banks, the supplier's bank | EUR to USDC with a licensed provider, transfer on a blockchain, conversion and payout by a local provider |
| What you pay | Sending fee, any intermediary fees, FX margin (1.4% on average for B2B), plus 0.7% to 1.1% if the receiving bank converts | Conversion spread going in, a network fee that is usually small, conversion spread going out (widest in exotic currencies) |
| Speed | Same day to several business days; often held up at the receiving bank | Minutes on-chain; the total depends on the local payout system |
| Hours | Business days and bank cut-offs | 24/7 on-chain; payout follows local system hours |
Example: what a EUR 20,000 payment costs (estimate)#
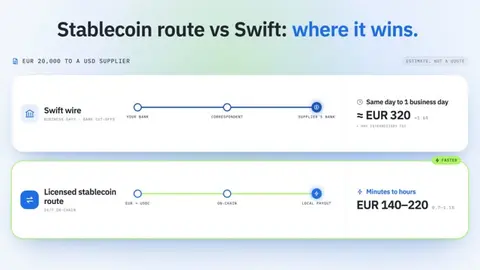
These figures are an estimate, not a quote. For Swift we use the FSB's 2025 average B2B cost of 1.6% for a major currency, and, for an exotic corridor, the 3.1% to 3.5% the FSB reports for retail payments (B2B, B2P and P2B) sent from sub-Saharan Africa, assuming a similar cost in the other direction. For the stablecoin route we assume conversion costs at both ends of 0.7% to 1.1% in total for a major currency and 1.6% to 3.6% for an exotic one, most of it at the far end, plus a negligible network fee.
| EUR 20,000 to | Swift cost | Swift time | Stablecoin route cost | Stablecoin route time |
|---|---|---|---|---|
| USD (major currency) | About 1.6%, around EUR 320, plus any intermediary fee | Same day to one business day | About 0.7% to 1.1%, EUR 140 to 220 | Minutes to hours, depending on payout |
| NGN or KES (exotic currency) | About 3.1% to 3.5%, EUR 620 to 700 | One to several business days | About 1.6% to 3.6%, EUR 320 to 720 | Minutes to hours, depending on local payout |
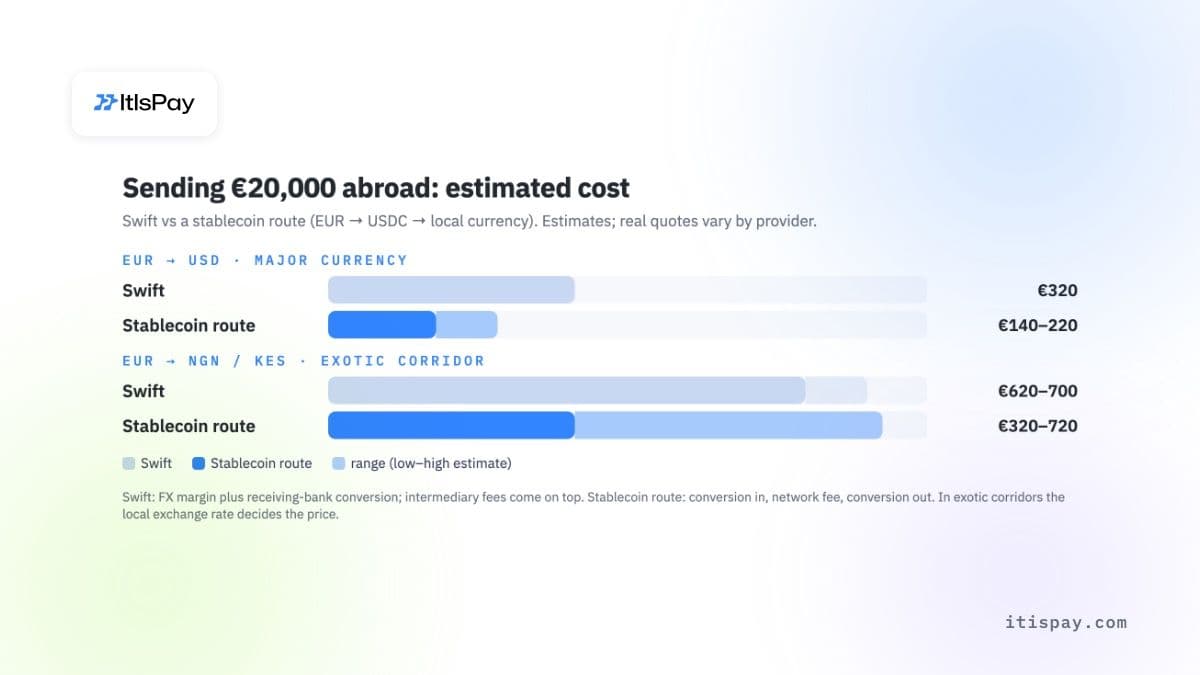
In the major corridor the stablecoin route saves one or two hundred euros. In the exotic corridor the ranges overlap: a well-priced local payout partner beats the wire, an expensive one costs more. Speed is the gain you can count on.
Corridor by corridor from the EU#
Swift speeds below are FSB 2025 figures for large payments (USD 100,000 and above) by receiving region, the closest public measure for supplier payments. Rules are as of October 2026.
| Corridor | How Swift performs | Stablecoin route | Verdict |
|---|---|---|---|
| SEPA (EUR) | SEPA Instant credits within 10 seconds, 24/7 | Two conversions for no gain | Not practical |
| United States | 73.1% credited within an hour | USDC is a US-issued dollar token; the gain is mainly weekends and holidays | Works |
| UAE | 32.3% credited within an hour | Foreign stablecoins cannot be accepted as payment for goods or services; conversion only through a UAE-licensed provider | Depends |
| Turkey | Ordinary wire corridor | Stablecoin withdrawals from Turkish platforms are capped at USD 3,000 a day and USD 50,000 a month (doubled where the platform applies additional verification), with a 48-hour hold on withdrawals (72 hours for the first one) | Not practical |
| Nigeria | Africa is the slowest region: 24.2% within an hour | Largest speed gain; needs a licensed local off-ramp; the securities regulator's stablecoin rules are still a proposal | Works |
| Kenya | Africa: 24.2% within an hour | Virtual asset law in force since November 2025, implementing rules being rolled out; mobile money payout through a licensed partner | Depends |
| India | Asia-Pacific: 25.6% within an hour | The Enforcement Directorate searched crypto on- and off-ramp firms under the foreign exchange law (FEMA) in June 2026 | Not practical |
| China | Asia-Pacific: 25.6% within an hour | A joint notice by the People's Bank of China and seven other agencies (February 2026) declares yuan-to-virtual-currency exchange business illegal on the mainland | Not practical |
| Philippines | Asia-Pacific: 25.6% within an hour | Conversion only through virtual asset service providers licensed by the central bank (BSP) | Depends |
| Mexico | Latin America: 42.7% within an hour | Payout over SPEI, Banco de México's instant system, which runs 24/7 | Works |
| Brazil | Latin America: 42.7% within an hour | From 1 October 2026, licensed cross-border payment (eFX) providers may not settle with foreign partners in virtual assets (BCB Resolution 561) | Not practical |
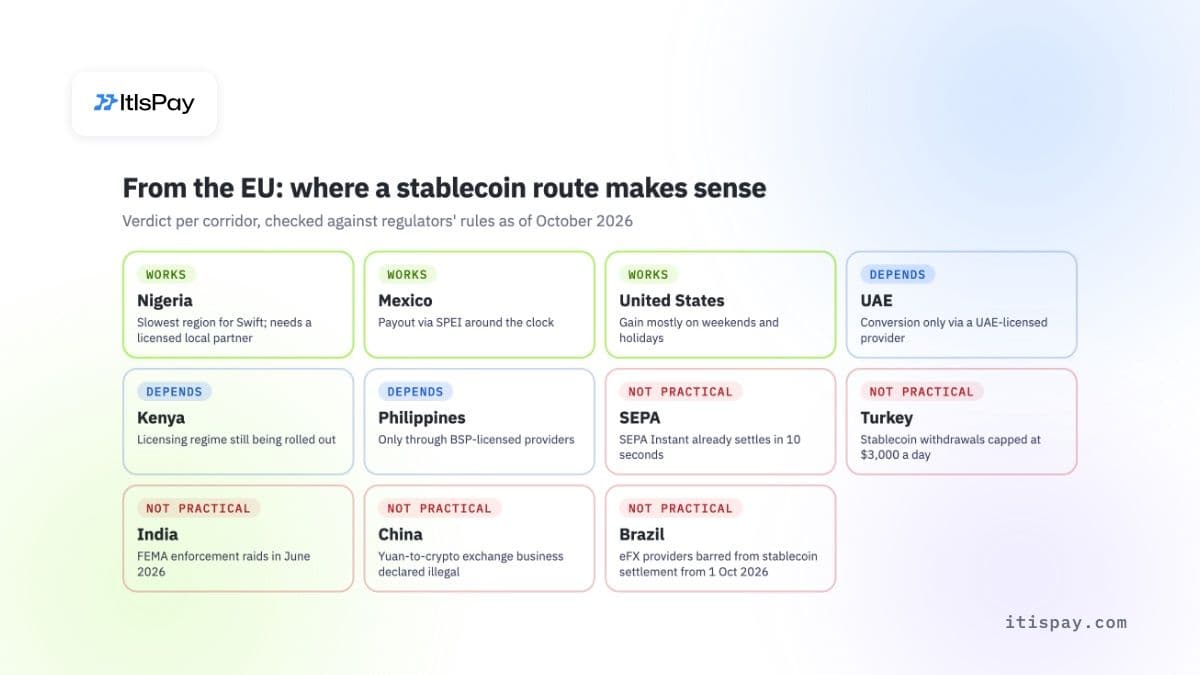
The route earns its place where Swift is slowest and local rules allow a licensed payout. Where the far end is closed, no amount of speed on-chain helps.
What does SEPA Instant change for payments inside Europe?#
Inside the euro payment area, the speed problem has a legal fix. The Instant Payments Regulation (EU) 2024/886 requires the payee's bank to make the money available "within 10 seconds" of receiving the payment order, 24 hours a day, every calendar day.
The deadlines are staggered:
- euro-area banks had to receive instant payments by 9 January 2025 and send them by 9 October 2025;
- payment institutions and e-money institutions in the euro area must send and receive by 9 April 2027;
- banks outside the euro area must receive by 9 January 2027 and send by 9 July 2027.
An instant transfer cannot cost more than a standard credit transfer of the same type (Article 5b), and from 9 October 2025 euro-area banks must check that the payee's name matches the IBAN before the money leaves, free of charge. That check alone removes a common cause of misdirected supplier payments.
The limit is in the name. SEPA Instant moves euros between accounts in SEPA countries. For a dollar invoice from Asia or a payment into Turkey or Latin America, you still choose between a Swift wire, a specialist provider with local accounts, or a stablecoin route. Receiving client money on a dedicated virtual IBAN helps with reconciliation on the euro side, but it does not change the payment channel the money arrives on.
Which B2B payment channel is fastest and cheapest?#
Put side by side, a European company has five payment channels to choose from. Speeds are typical ranges from the sources above, not guarantees.
| Channel | Typical speed | Main cost | Operating hours | Works best for |
|---|---|---|---|---|
| Swift wire via correspondent banks | Same day to several days | FX margin, intermediary and receiving fees | Business days, bank cut-offs | Large payments in any currency |
| SEPA credit transfer | By the next business day | Low fixed fee | Business days | Routine EUR payments in SEPA |
| SEPA Instant | Within 10 seconds | Same as a standard transfer | 24/7, every day | Urgent EUR payments in SEPA |
| Specialist provider with local accounts | Minutes to one day | FX margin, platform fee | Depends on local payment systems | Frequent payments in major currencies |
| Licensed stablecoin settlement | On-chain transfer at any hour, plus conversion at each end | Conversion spread at each end, network fee | 24/7 on-chain; EUR leg depends on the bank transfer | Non-SEPA corridors, weekends, USD suppliers |
When does stablecoin settlement help cross-border B2B payments?#
Beyond the corridor table, a licensed stablecoin route helps in four situations:
- A software firm collects from clients in markets with few correspondent links. The transfer skips the chain of intermediaries.
- A payment cannot wait for Monday. If the euro leg runs over SEPA Instant, money can land on an IBAN on a Sunday.
- A supplier prices in USD and you have no dollar account. Paying in USDC avoids opening and funding one abroad.
- A PSP pays out in several countries. It can move liquidity between partners without keeping idle prefunded balances in each one.
In the EU, the most liquid MiCA-compliant options are USDC and EURC; other e-money tokens include SG-Forge's EURCV. Circle Internet Financial Europe SAS received an e-money institution licence from France's ACPR on 1 July 2024 and issues both tokens under MiCA, the EU's Markets in Crypto-Assets Regulation. According to market data from DeFiLlama (7 October 2026), USDC supply stood at about USD 73.8 billion and all euro stablecoins together at about EUR 0.83 billion, of which EURC was about EUR 0.48 billion. Euro stablecoins remain small. That matters if you need deep liquidity when converting large amounts.
The model only works if a licensed party does the conversion and holds the funds. Your company sends or receives euros; an EU-licensed crypto-asset service provider (CASP) converts them and handles the transfer. We describe the setup for supplier and client flows in our guide to B2B crypto payments. On the receiving side, a crypto-to-fiat payment gateway converts incoming stablecoins and pays out euros to your account.
When do stablecoins not help, and what do EU rules say?#
Risks to keep in mind
- USDT cannot be exchanged by EU-licensed providers; use MiCA-compliant tokens such as USDC or EURC.
- In exotic currencies the exchange rate at the payout end can erase the price advantage; the reliable gain is speed.
- The recipient needs a licensed local provider to receive local currency; without one the problem moves to your supplier.
- Each corridor needs a local legal check before you route real volume.
Stablecoins are not a cheaper SEPA: between two euro accounts, two conversions only add cost. Each conversion carries a spread, and there is no independent benchmark for this cost in the EU, so compare quotes on your real amounts. Your supplier also needs a regulated provider in its own country that converts stablecoins. Without one, you have only moved the problem to their side.
Then come the EU rules:
- After ESMA's statement of 17 January 2025, EU-licensed CASPs stopped offering exchange services in stablecoins that do not comply with MiCA, which in practice meant USDT. Custody and transfer can continue, but a company that wants euros out should not plan around USDT.
- MiCA Article 23, applied to non-euro e-money tokens by Article 58(3), requires the issuer to stop issuing if the token's use as a means of exchange in one currency area exceeds 1 million transactions and EUR 200 million a day.
- Since 30 December 2024, Regulation (EU) 2023/1113 requires CASPs to send payer and payee information with every crypto transfer, with no minimum amount.
- Under the EBA's June 2025 no-action letter, a CASP that transfers or holds e-money tokens for clients as a payment service also needs a payment or e-money licence, or a partnership with a licensed payment provider; the transition period ran until 1 March 2026.
Stablecoins also carry their own risk. The ECB's November 2025 Financial Stability Review warns that a stablecoin's "primary vulnerability is that investors lose confidence that they can be redeemed at par."
ESMA's executive director Natasha Cazenave told the European Parliament in April 2025, repeating ESMA's earlier warning, that "despite MiCA, there will be no such thing as a safe crypto-asset." For a treasury team, that means keeping stablecoin balances short-lived and converting to euros on receipt unless there is a reason to hold.
Do you need a licence for cross-border payments?#
Not if you are paying for your own purchases or collecting for your own sales. The licence belongs to whoever moves other people's money. Under the EU Payment Services Directive (PSD2, Article 37), only authorised payment service providers may offer payment services. Under MiCA, Article 59, only an authorised crypto-asset service provider (CASP), or a bank or other financial firm allowed to do so under Article 60, may exchange or transfer crypto-assets for clients.
In practice:
- A company that pays its suppliers or receives payments from its own clients uses a licensed bank or provider. It does not need a licence of its own.
- A PSP, marketplace or platform that collects or pays out on behalf of other businesses needs a payment or e-money licence, or must work under a licensed partner.
- A firm that exchanges or sends stablecoins for clients needs MiCA authorisation as a CASP. If it handles e-money tokens as a payment service, it also needs a payment licence or a licensed payment partner, as the EBA position above explains.
- When a provider offers a "cross-border payment API", ask whose licence the money moves under and check that licence in the national register or the ESMA register.
How do you choose a setup for your business payment flows?#
Start from your list of cross-border B2B payments, not from the technology. Sort the last twelve months of supplier and client payments by corridor, currency and urgency, then match each group to a payment channel:
- EUR payments within SEPA: SEPA Instant, once your bank or provider supports it.
- Large payments in major currencies: Swift or a specialist provider, with the FX rate quoted separately from the fee.
- Frequent USD payments, or corridors marked "Works" in the table above: test a licensed stablecoin route on one corridor, with euros in and out.
For any provider, ask for the full cost on a real amount, the expected delivery time, how you can track the payment, and, for stablecoin routes, the licence numbers in the ESMA register and the provider's payment licence. I would run the stablecoin route alongside the existing bank route for a quarter before moving volume. The numbers from your own corridors will tell you more than any average.
If your clients abroad want to pay in USDC or other stablecoins and you want euros on your account, ItisPay provides the API, invoicing and reconciliation. Licensing, KYC and settlement to your IBAN run through our EU-licensed CASP + Payment Institution partner, and onboarding, from KYB to first transaction, can be completed in under a week.
This article is for informational purposes only and does not constitute legal or regulatory advice.

